 100% online
 Your Spanish home, sorted.


Modelo 210 form in English: every box, explained
The official form, as approved in the Boletín Oficial del Estado, is in Spanish. Here is the Modelo 210 form in English, box by box, for a home you own in Spain: what goes where if it isn't rented out, if you rent it or if you sold it, with a worked example and the boxes that change in 2027.
By the CasitaTax team · Updated October 30, 2026 · 12 min read
In short
 There is no blank PDF to fill in by hand: you fill in the Agencia Tributaria's online form, which files the return or prints it as a PDF.
- Home not rented out: income type 02, section 210 I. Box 4 is your share of 1.1% or 2% of the cadastral value; box 21 is the rate, 19% in the EU and the EEA, 24% elsewhere.
- Rent: code 01 (35 for several tenants grouped), section 210 R. Sale: code 28, section 210 H, with the buyer's Modelo 211 number and the 3% withheld in box 29.
- From January 1, 2027, every return uses a new form, with the number of days, your share and, for rent, an annex of expenses.
On this page
Where is the Modelo 210 form, and is there an English version?
On the Agencia Tributaria's website, as an online form: there is no blank PDF to download and fill in by hand. The order that approves Modelo 210 only accepts a paper return printed by the tax office's own service after you fill in its online form, and corrections made by hand on the printout have no effect.
- Online: you identify yourself with Cl@ve, a digital certificate, a Spanish electronic ID card or a European eIDAS identity, fill in the form, and file it and pay in the same session.
- On paper (the predeclaración): the same online form prints the return as a PDF. Write your NIF on every copy of the payment page, sign them, then pay or file as the PDF's instructions say.
The form, as the Boletín Oficial del Estado approves it, is in Spanish, but the Agencia Tributaria publishes its instructions in English. This guide follows them for the boxes a home owner uses, and leaves out those for dividends, royalties or pensions.
If you have no NIE, the paper route's form has a button next to the NIF field that gives you an identification code (a NIF M): keep it, it is your number for every later return.
Good to know
Fields with an asterisk are mandatory. Before filing, press "Validar declaración": the form lists what is wrong, and "Ir al Error" takes you to each field to fix.
Which part of the form do you fill in?
The part for what your home did during the year. Spain taxes each income on its own, so each owner usually files their own return, and a home that was empty part of the year and rented out the rest needs at least two.
Home not rented out (empty, or used by you)
- Income type (box 2)
- 02
- Section
- 210 I
- Boxes
- 4
Rented out
- Income type (box 2)
- 01, or 35 for several tenants grouped
- Section
- 210 R
- Boxes
- 5 to 8
Sold
- Income type (box 2)
- 28
- Section
- 210 H
- Boxes
- 9 to 17
| Your situation | Income type (box 2) | Section | Boxes |
|---|---|---|---|
| Home not rented out (empty, or used by you) | 02 | 210 I | 4 |
| Rented out | 01, or 35 for several tenants grouped | 210 R | 5 to 8 |
| Sold | 28 | 210 H | 9 to 17 |
A return uses only one of the sections 210 I, 210 R, 210 G and 210 H; 210 G is for gains on anything other than property, such as shares.
What goes at the top: who files, the dates and the income?
Your own details, the date of the income and its type. For a home, the owner is always the one filing, even when a gestor sends the return for them.
Persona que realiza la autoliquidación (who files)
Your NIF (your NIE, or the code the form gives you) and your name, surnames first. Tick S, Contribuyente: for rent, a home not rented out and a sale, the order requires the owner here.
Devengo (when the income arose)
- Home not rented out: leave Agrupación empty; in Período/Año, 0A and the tax year; in Fecha de devengo, the last day of that year (December 31): 31/12/2025 for the 2025 return.
- Rent of the whole year: tick Agrupación, then 0A and the year. Rent filed separately: the date each rent fell due, or was paid if earlier.
- Sale: the date of the sale, with 0A and its year.
The tax office's help pages ask you to pay special attention to this block: if the form refuses the period, check it first.
Renta obtenida (the income)
Box 2, the income type: 02, 01, 35 or 28, as in the table above. Box 3, the currency you were paid in, from the form's list: 954 for the euro.
How do you fill in your details and your home's?
Your details as the owner and your address abroad, then the address and the cadastral reference of the Spanish home.
- Contribuyente: your NIF; F (an individual); surnames, then first name; your tax number in your country, if you have one; your date and place of birth; and in box 1, your country of tax residence, from the form's list of codes. That country sets your rate in box 21.
- Your address abroad (boxes 49 to 58): street, town, postcode, region, country, email and phone numbers where the tax office can reach you.
- Representative (boxes 31 to 48): leave it empty unless you named a representative in Spain, or want letters sent to an address in Spain. The law requires one only in some cases (article 10 of the non-resident tax law); otherwise it is optional.
- Pagador / Adquirente: empty for a home not rented out and for code 35; the tenant for code 01; after a sale, the buyer (the one named on the Modelo 211 if there are several).
- Situación del inmueble (the same address boxes, 31 to 45, as the representative's block: address boxes have their own numbers, apart from the calculation's): the Spanish home's address, and in box 60 its referencia catastral, printed on the IBI bill or found at the Sede Electrónica del Catastro.
How do you fill in the form for a home you don't rent out?
In section 210 I, a single box: box 4, the taxable base. It is your share of a notional income, a percentage of the home's cadastral value, with no expense deducted.
- 1Take the home's cadastral value, on the IBI bill.
- 2Apply 1.1% if the town's cadastral values were revised in a general valuation in force since 2012, 2% otherwise (rules for 2025).
- 3Multiply by your share of the ownership, as the title deed states it.
- 4If you didn't own the home all year, or rented it out for part of it, multiply by the days it was yours and not rented, divided by the days in the year.
- 5Write the result in box 4, in euros and cents.
A worked example
A villa with a cadastral value of €120,000, in a town whose values were revised since 2012, owned 50% each by a couple living in the EU and not rented out all year. Each of them files this return:
2
- What it is
- Tipo de renta: the income type
- Each owner writes
- 02
4
- What it is
- Base imponible: €120,000 × 1.1% × 50%
- Each owner writes
- €660.00
21
- What it is
- Tipo de gravamen: the rate of an EU resident
- Each owner writes
- 19%
22
- What it is
- Cuota íntegra: box 4 × box 21
- Each owner writes
- €125.40
24 and 28
- What it is
- The same tax, before and after treaty limits
- Each owner writes
- €125.40
29
- What it is
- Retenciones: tax already withheld
- Each owner writes
- 0
31
- What it is
- Resultado: the tax to pay
- Each owner writes
- €125.40
| Box | What it is | Each owner writes |
|---|---|---|
| 2 | Tipo de renta: the income type | 02 |
| 4 | Base imponible: €120,000 × 1.1% × 50% | €660.00 |
| 21 | Tipo de gravamen: the rate of an EU resident | 19% |
| 22 | Cuota íntegra: box 4 × box 21 | €125.40 |
| 24 and 28 | The same tax, before and after treaty limits | €125.40 |
| 29 | Retenciones: tax already withheld | 0 |
| 31 | Resultado: the tax to pay | €125.40 |
To get these figures for your own home, try the free non-resident tax in Spain simulator.
We file your Modelo 210
 Every owner, every year
- You approve before we file
- 100% online
What changes for a home you rent out?
You fill in section 210 R instead: box 5 for the rent, box 7 for expenses, box 8 for the taxable base, box 5 minus box 7.
- Box 5: the gross rent of the period you declare.
- Box 7: the expenses of the rented period, only for residents of the EU, Iceland, Norway and Liechtenstein, with a tax residence certificate from their country attached. Everyone else, the United Kingdom included, leaves it at zero: the law taxes their gross rent, a rule the Tribunal Supremo is now reviewing.
- Box 6 is for dividends only: leave it empty.
- Income type: 01 for rent, return by return or grouped for one tenant; 35 to group the rent of several tenants of the same home, when none of them withholds tax.
- Pagador: for code 01, the tenant's NIF and name.
The days the home wasn't rented go on a separate return in section 210 I, with the days cut as in step 4 above. When each rental return is due: our guide to the Modelo 210 deadline.
How do you fill in the return after selling?
In section 210 H, with income type 28. The return declares the gain and offsets the 3% of the price the buyer withheld.
- Box 9, sale value: the price, minus the costs and taxes of the sale that you paid.
- Box 10, purchase value: the price you paid, plus its costs and taxes but not mortgage interest, minus the depreciation deducted if you rented the home out.
- Box 11: box 9 minus box 10. Box 12, the gain: usually the same figure. Box 17, the base: box 12, plus box 16 if you bought in two steps or improved the home in a later year (boxes 13 to 16).
- Dates and the Modelo 211: the dates you bought, and the receipt number printed on the buyer's Modelo 211, which the buyer must give you.
- C/O and your share: a married couple who are both non-resident can file a single return (C, for joint), each with their share; otherwise O, and your share alone.
- Box 21: 19%, wherever you live. Box 29: the amount the buyer withheld.
If box 31 comes out negative, the tax office owes you the difference: it is written with a minus sign, and you give an account for the refund on the payment page. Declare a sale at a loss too: it is how you get the 3% back.
Watch out
A home bought before 1995 (a partial reduction of the gain), or a main home in Spain sold by an EU or EEA resident who reinvests the price in a new main home (codes 33 and 34), has rules of its own: check them before filing.
What goes in boxes 21 to 31?
The calculation, the same on every return: the rate, the tax, what was already paid, the result. Every amount is in euros, with two decimals.
19, 20
- On the form
- Exenciones
- What to write
- Empty, unless you claim an exemption
21
- On the form
- Tipo de gravamen
- What to write
- 19% for residents of the EU, Iceland, Norway and Liechtenstein, 24% for everyone else; 19% on the gain from a sale
22
- On the form
- Cuota íntegra
- What to write
- Box 4, 8 or 17 × box 21; never below zero
23
- On the form
- Deducción por donativos
- What to write
- Gifts that qualify under Spanish income tax rules, if any
24
- On the form
- Cuota Ley IRNR
- What to write
- Box 22 − box 23
25 to 27
- On the form
- Convenio
- What to write
- Usually empty for a home: treaties generally set no limit on income from property
28
- On the form
- Cuota íntegra reducida
- What to write
- Box 24 − box 27
29
- On the form
- Retenciones
- What to write
- Tax already withheld: the buyer's 3% after a sale, usually zero otherwise
30
- On the form
- Ingreso/Devolución anterior
- What to write
- Only on a corrective return
31
- On the form
- Resultado
- What to write
- Box 28 − box 29 + box 30: the tax to pay or, with a minus sign, the refund
| Box | On the form | What to write |
|---|---|---|
| 19, 20 | Exenciones | Empty, unless you claim an exemption |
| 21 | Tipo de gravamen | 19% for residents of the EU, Iceland, Norway and Liechtenstein, 24% for everyone else; 19% on the gain from a sale |
| 22 | Cuota íntegra | Box 4, 8 or 17 × box 21; never below zero |
| 23 | Deducción por donativos | Gifts that qualify under Spanish income tax rules, if any |
| 24 | Cuota Ley IRNR | Box 22 − box 23 |
| 25 to 27 | Convenio | Usually empty for a home: treaties generally set no limit on income from property |
| 28 | Cuota íntegra reducida | Box 24 − box 27 |
| 29 | Retenciones | Tax already withheld: the buyer's 3% after a sale, usually zero otherwise |
| 30 | Ingreso/Devolución anterior | Only on a corrective return |
| 31 | Resultado | Box 28 − box 29 + box 30: the tax to pay or, with a minus sign, the refund |
What is the payment page at the end?
The documento de ingreso o devolución: it repeats box 31 and says how you pay, or where the refund goes.
- To pay: direct debit (not after a sale), card or a Spanish bank, or a transfer from abroad with a payment reference. The dates and the details of each are in our guide to the Modelo 210 deadline.
- A refund: an account in your own name, in Spain or abroad, with its IBAN and BIC.
- Nothing to pay or refund: tick cuota cero.
If you'd rather not go through the form at all, we file your Modelo 210 and tell you what to pay.
What changes on the form in 2027?
Every return filed from January 1, 2027 uses a new version of the form, whatever its tax year: a 2025 return filed late in 2027 too. Orden HAC/623/2026 adds:
- N.º de días: the days the home was at your disposal (210 I) or rented out (210 R).
- Cuota participación: your share of the ownership, as a percentage.
- Clave de referencia catastral (box 61): 1 if the home has a cadastral reference, 2 if it doesn't.
- An annex of expenses for rent: box 7 line by line (interest, repairs, community fees, utilities, insurance, local taxes, depreciation…), interest and repairs capped at the rent.
- C/I instead of C/O for a couple's sale, a box to tell an improvement from a second purchase, and no signature field on the return.
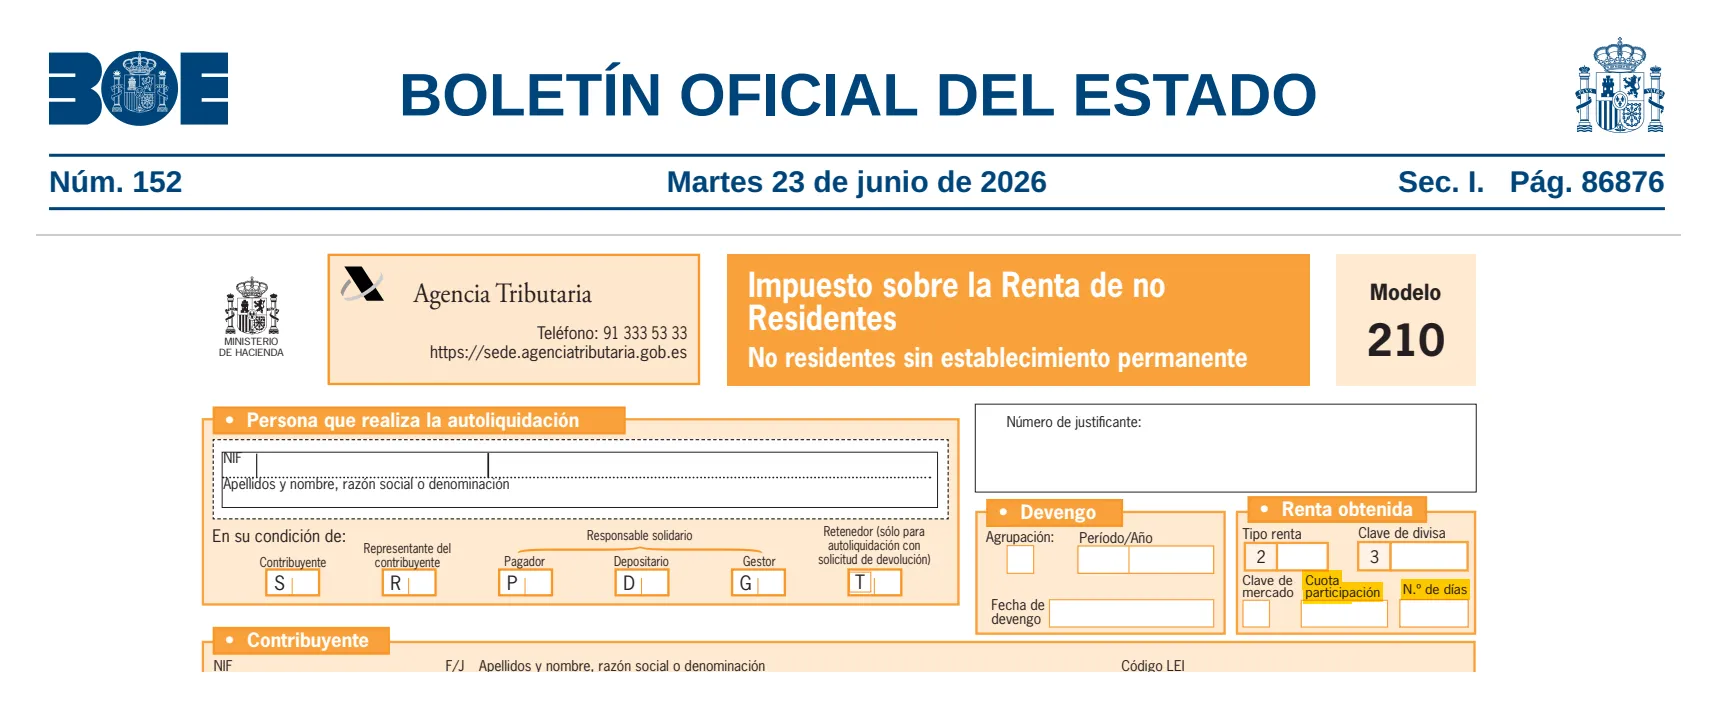
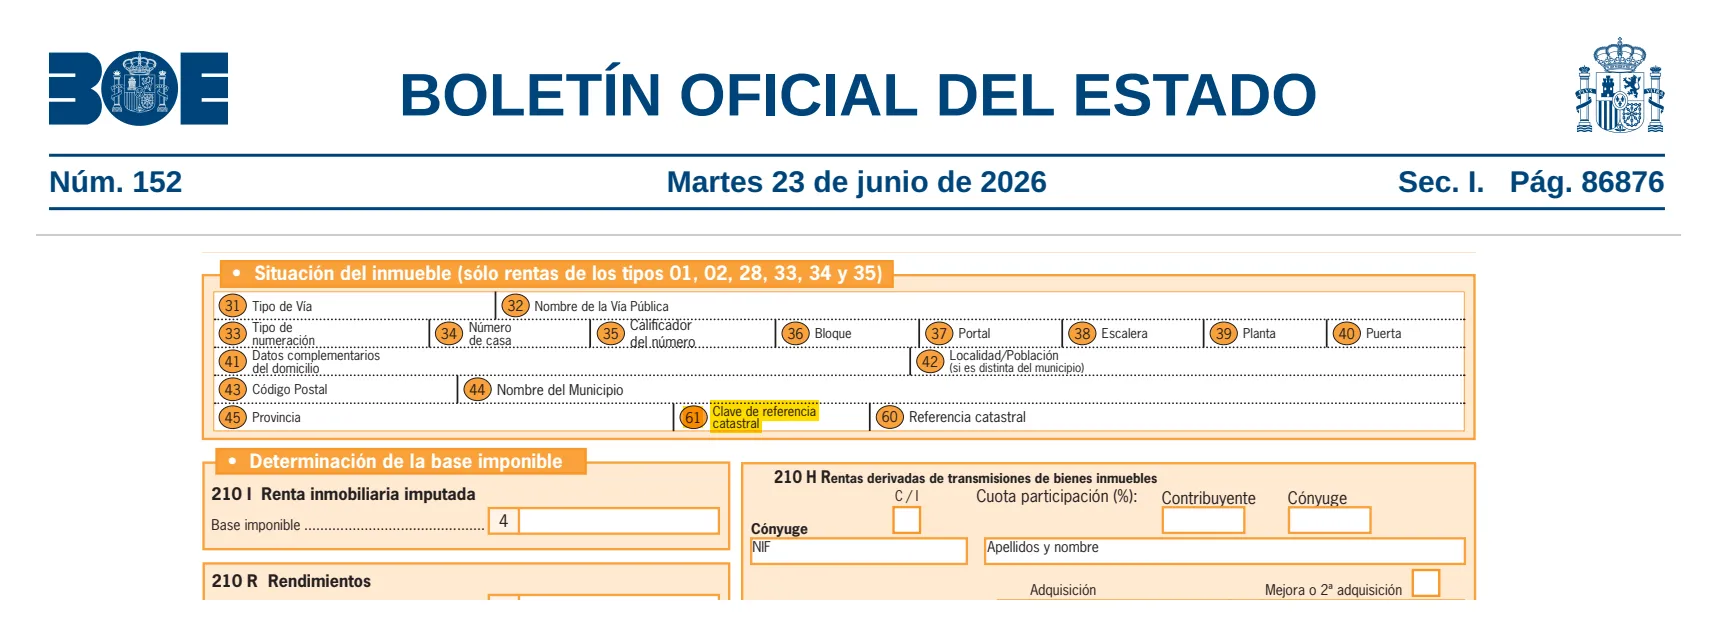
The Agencia Tributaria hasn't published its instructions for the new boxes yet; this guide will follow them when it does.
What if you made a mistake on a return you filed?
If you paid too little, or got too much back, file a corrective return (autoliquidación complementaria): the whole return again, with every figure right.
- Tick "Autoliquidación complementaria" and give the receipt number (número de justificante) of the first return.
- In box 30, what the first return paid, with a minus sign, or the refund you already received for it, with a plus sign (empty if the refund hasn't arrived).
- Box 31 then shows only the difference.
A corrective return filed after the deadline leads to the surcharges for filing late, which the tax office bills separately: see what filing late costs.
How we checked this guide
We read the official texts below and update this guide whenever the rules change. It is general information, not advice on your own situation.
- Agencia Tributaria, Modelo 210: instrucciones — read on October 30, 2026
- Agencia Tributaria, Form 210: instructions (English) — read on October 30, 2026
- Agencia Tributaria, formulario del modelo 210 para presentación en papel — read on October 30, 2026
- Agencia Tributaria, presentación electrónica del modelo 210 — read on October 30, 2026
- Orden EHA/3316/2010, modelos 210, 211 y 213 (texto consolidado: arts. 2 y 10, anexo I) — read on October 30, 2026
- Orden HAC/623/2026, de 12 de junio (BOE-A-2026-13573): nuevo modelo 210 — read on October 30, 2026
- Real Decreto Legislativo 5/2004, texto refundido de la Ley del IRNR (arts. 24, 25 y 27) — read on October 30, 2026


