 New


VAT on short term lets in Spain: which lets pay it, and which stay exempt
VAT on short term lets in Spain starts on December 1, 2026: a furnished home let to the same guest for 30 nights or fewer pays 10%, unless it is where the owner lives. Lets with hotel services pay it whatever their length; longer lets stay exempt. Here is how to tell which of your lets pay, case by case.
By the CasitaTax team · Updated November 13, 2026 · 8 min read
In short
 From December 1, 2026, a furnished home let to the same guest for 30 nights or fewer pays VAT at 10%, under Real Decreto-ley 29/2026, ratified on November 12, 2026.
- Lets with hotel services (cleaning or linen during the stay, meals) already paid VAT, and still do, whatever their length.
- Still exempt: lets of more than 30 nights without hotel services, and short lets of the home the owner lives in, without hotel services.
- Cleaning and linen at arrival and departure don't count as hotel services.
- Once your lets pay VAT, you register, file a VAT return each quarter and a yearly summary; your Modelo 210 goes on as before.
On this page
Which lets pay VAT from December 1, 2026?
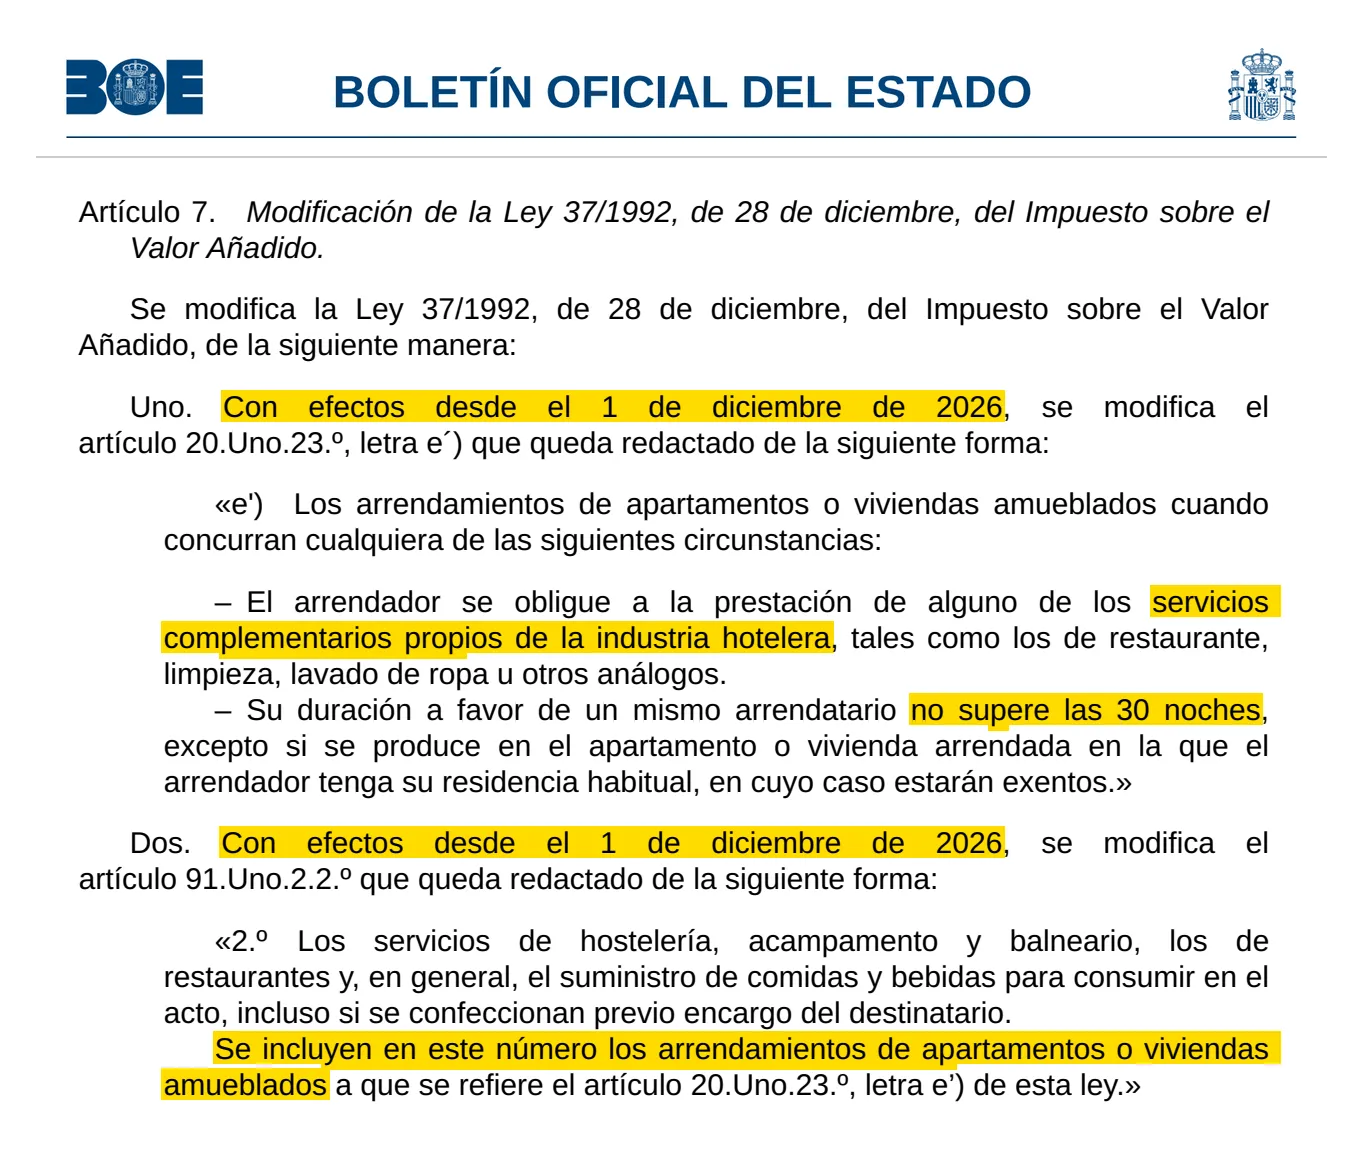
Two kinds of let of a furnished home, under the new wording of the VAT law (Ley 37/1992, article 20.Uno.23.º e'), set by Real Decreto-ley 29/2026:
- A let of 30 nights or fewer to the same guest, unless the home is the owner's habitual residence. This is what is new: until then, such a let without services was exempt.
- A let with hotel services, such as cleaning during the stay, laundry or meals, whatever its length. These lets already paid VAT before the change.
Both pay the reduced rate, 10%, from December 1, 2026. A let of more than 30 nights without hotel services stays exempt.
A week in August to a family, cleaning when they leave
- VAT from December 1, 2026
- Yes, 10%
Exactly 30 nights to one guest
- VAT from December 1, 2026
- Yes, 10%
Three months to a remote worker, no services
- VAT from December 1, 2026
- No, exempt
Three months with weekly cleaning and fresh linen
- VAT from December 1, 2026
- Yes, 10% (hotel services)
A school year to a student, no services
- VAT from December 1, 2026
- No, exempt
Your own home, the one you live in, for two weeks, no services
- VAT from December 1, 2026
- No, exempt
A home in the Canary Islands, Ceuta or Melilla
- VAT from December 1, 2026
- No VAT there (the Canary Islands have IGIC)
| Your let | VAT from December 1, 2026 |
|---|---|
| A week in August to a family, cleaning when they leave | Yes, 10% |
| Exactly 30 nights to one guest | Yes, 10% |
| Three months to a remote worker, no services | No, exempt |
| Three months with weekly cleaning and fresh linen | Yes, 10% (hotel services) |
| A school year to a student, no services | No, exempt |
| Your own home, the one you live in, for two weeks, no services | No, exempt |
| A home in the Canary Islands, Ceuta or Melilla | No VAT there (the Canary Islands have IGIC) |
How are the 30 nights counted?
Per guest and per let: the law says a let whose length "to the same tenant" doesn't exceed 30 nights. A let of exactly 30 nights pays VAT; one night more and, without hotel services, it stays exempt.
The rule looks at each let, not at your year: a home let ten times a summer for a week each has ten lets that pay VAT, and the same home let for the winter to one tenant has one that doesn't.
Watch out
Neither the decree nor the Agencia Tributaria says, so far, how two bookings by the same guest back to back are counted. Don't split or join stays to land on one side of the line: write each let's real dates in the booking and the contract.
What counts as a hotel service?
Services that go beyond handing over the keys, the ones a hotel gives during the stay. The law names restaurant, cleaning and laundry, or similar. In a binding answer to a non-resident who let a home by the week (V1338-17), the Dirección General de Tributos drew the line. What counts is what the owner commits to in the let.
Hotel services
- Cleaning inside the home every week
- Changing the linen every week
- Reception and attention to guests throughout the stay
- Meals, laundry
Not hotel services
- Cleaning at each guest's arrival and departure
- Changing the linen at arrival and departure
- Cleaning the building's common areas
- Repairs and maintenance when something breaks
That owner's weekly lets were exempt then. From December 1, 2026, the same lets pay VAT anyway, as they last 30 nights or fewer: for most holiday lets, the line on services now matters only for lets longer than 30 nights.
Which lets stay exempt from VAT?
The exemption for letting a home as housing still covers:
- Lets of more than 30 nights to the same tenant without hotel services: a season, a school year, a long let.
- Short lets of the home the owner lives in, when it is the owner's habitual residence and the let comes without hotel services.
- Unfurnished homes let as housing, as we read it: the new rule names furnished flats and homes only.
And the Canary Islands, Ceuta and Melilla are outside Spanish VAT altogether: the VAT law doesn't apply there. The Canary Islands have their own indirect tax, the IGIC, with rules of its own that this guide doesn't cover.
An exempt let is still taxed as income: the rent goes on your Modelo 210, as it always has.
Does the exception for the owner's own home cover a holiday home?
Generally not. The exception covers a let "in the flat or home in which the lessor has their habitual residence": someone who lives in Spain and lets their home for a fortnight while away. A home you own in Spain and live in only for holidays is not your habitual residence, so for most owners who live abroad, the exception doesn't apply.
It also covers only the short-let case: a let with hotel services pays VAT even in the owner's own home.
How much VAT, and on what price?
10%, the reduced rate of hotels and restaurants, not the general rate of 21%. It applies to the whole price the guest pays for the stay; as we read the law, that includes what you charge with it, such as a cleaning fee.
A platform's or a manager's commission is another service, billed to you, with VAT rules of its own.
What do you have to do once your lets pay VAT?
Run it as a small business, for VAT only. The VAT law treats every lessor as a business, even with a single home:
- 1Register with the Agencia Tributaria: the law asks for a declaration when an activity subject to VAT starts.
- 2Charge VAT on your lets and issue an invoice for each of them.
- 3File a VAT return each quarter: the VAT your guests paid, less the VAT you paid on expenses for the lets, and pay the difference.
- 4File a yearly summary at the start of the next year.
The first returns cover the quarter that holds December 1, 2026, and fall at the start of the following year. Our page on VAT holiday rental in Spain sets out the service and its price.
We file your holiday-let VAT
 Registration: Modelo 036
- Each quarter's Modelo 303
- We pay it, you get the proof
What about stays booked and paid before December 1, 2026?
The decree has no rule of its own for them. Under the VAT law, the VAT on a let falls due when each payment is due, and a payment received in advance is taxed when it is received; but whether a deposit received before December 1, 2026, while such lets were exempt, for a stay after it, pays VAT, neither the decree nor the Agencia Tributaria has said so far.
Good to know
Keep, for every stay from December 1, 2026 on, the date it was booked, each payment and its date. They decide which return a payment belongs to, whatever the answer.
Does VAT change your Modelo 210?
No: VAT is a tax your guests pay through you; the income tax on the rent is yours, and goes on as before. Each owner still declares the rent on Modelo 210, at the rates and on the dates of the Modelo 210 for a home you rent out, and the days the home isn't let still carry the tax on an empty home in Spain.
To see what the income tax comes to, the non-resident tax in Spain simulator works it out. The other taxes on a home you let, such as the IBI, are in our guide to property taxes in Spain for non residents.
Is the new VAT on holiday lets final?
Yes. Real Decreto-ley 29/2026 has been in force since October 2026, and the Congreso ratified it on November 12, 2026; its VAT articles take effect on December 1, 2026. The Agencia Tributaria lists the change among its 2026 VAT news, at the rate of 10%.
How we checked this guide
We read the official texts below and update this guide whenever the rules change. It is general information, not advice on your own situation.
- Real Decreto-ley 29/2026, de 6 de octubre (art. 7, BOE-A-2026-20823) — read on November 12, 2026
- Ley 37/1992, del Impuesto sobre el Valor Añadido (arts. 3, 5, 20.Uno.23.º, 75, 78, 90 y 91) — read on November 12, 2026
- Real Decreto 1624/1992, Reglamento del IVA (art. 71) — read on November 12, 2026
- Agencia Tributaria, Novedades de normativa 2026: Real Decreto-ley 29/2026 — read on November 12, 2026
- Dirección General de Tributos, consulta vinculante V1338-17, de 31 de mayo de 2017 — read on November 12, 2026
- Congreso de los Diputados, 130/000060: Real Decreto-ley 29/2026, convalidado — read on November 12, 2026


